All Categories
Featured
Understanding How Indexed Universal Life Policies Secure ...

Understanding 2026 Medicare Benefit Options and Seniors

How Term Life Protects Family Wealth
Table of Contents
An HMO Medicare Benefit plan provides a network (described as an "HMO network") of health care companies and health centers to its customers. It's needed for a client to choose a primary care doctor to manage their healthcare and provide referrals to any companies that are not in the plan's network, other than in case of an emergency situation.
The ease of having a main care doctor to coordinate and handle the care provided. A client can only see providers within the plan's network unless they have a referral for an outdoors expert, or it's an emergency scenario.
Nevertheless, unlike an HMO strategy, a PPO Medicare Advantage strategy enables more flexibility when seeing out-of-network service providers. Therefore, it's not needed to have a referral to see an out-of-network expert although it might be more costly and take additional time to get insurance coverage because a patient must submit a claim for coverage each time they see an out-of-network supplier.
The patient has more versatility with which suppliers they select to see, whether they're within the strategy's network or out-of-network. The client is accountable for handling their health care instead of a main care company.
An EPO insurance coverage strategy, or an 'Exclusive Provider Organization' insurance strategy, is often called a strategy that is "located in between an HMO and PPO." This is because, like a PPO plan, an EPO does not need a client to stay in-network for care meaning, no recommendations or emergencies are essential for seeing an out-of-network company.
Optimizing Indexed Universal Life Policy Benefits for Retirement
This strategy is less widely known, it typically supplies a much larger network than an HMO.A POS insurance coverage strategy, or a 'Point of Service' insurance plan, is likewise known to "blend aspects of HMO and PPO plans." This is because, like an HMO plan, a POS insurance coverage plan needs a client to have a primary care doctor that manages their health care and provides referrals to out-of-network specialists or suppliers.
, the deductible is at least $1,400 for a specific and $2,800 for a household. In order to fight the high deductible cost, it is advised that a patient contributes to an HSA/HRA or a 'Health Savings Account'/'Health Compensation Plan,' which companies frequently contribute to annually.
Another element to keep in mind about this strategy is that it secures the client from "disastrous out-of-pocket expenses for covered services." What this suggests is that, once a client's "annual out-of-pocket costs for covered services from in-network companies, including deductibles, copayments, and coinsurance, reaches the predetermined devastating limitation," the insurance company will cover all expenses.
HMO and PPO strategies share particular functions. There are some primary distinctions in between HMO and PPO plans.
Maximizing IUL Policy Benefits in Retirement
HMOs will not cover care from an out-of-network supplier. HMOs usually have lower premiums and out-of-pocket expenses.
It's good to have choices. When it comes to medical insurance, you have your choice of a number of plan types. 2 popular types you'll frequently see are HMO and PPO. Differences in between HMO (Health Care Organization) and PPO (Preferred Service provider Company) strategies consist of network size, capability to see specialists, expenses, and out-of-network protection.
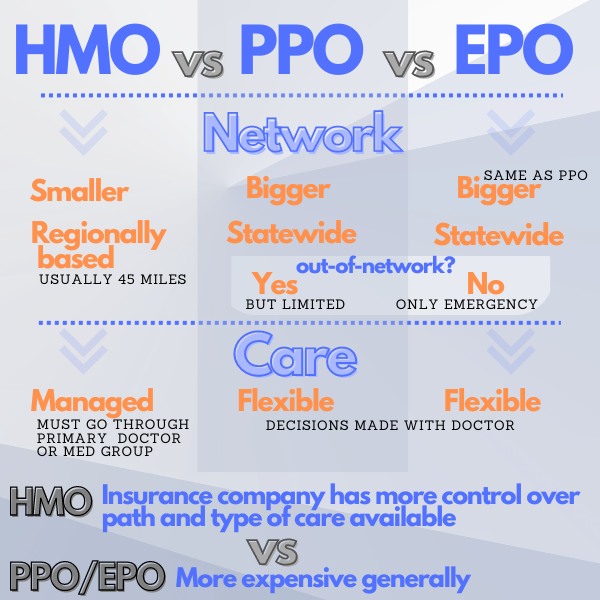
An HMO offers you access to certain medical professionals and health centers within its network. A network is made up of suppliers that have actually consented to lower their rates for plan members and likewise satisfy quality standards. However unlike PPO strategies, care under an HMO strategy is covered just if you see a company within that HMO's network.

Latest Posts
Understanding How Indexed Universal Life Policies Secure Retirement
A Complete Guide to 2026 Medicare Benefits
How Term Life Protects Family Wealth